How much should you budget for closing costs?
Per Fannie Mae, closing costs usually range from 2% to 5% of the value of your mortgage and are paid in addition to your down payment. Try Fannie Mae’s closing costs calculator.
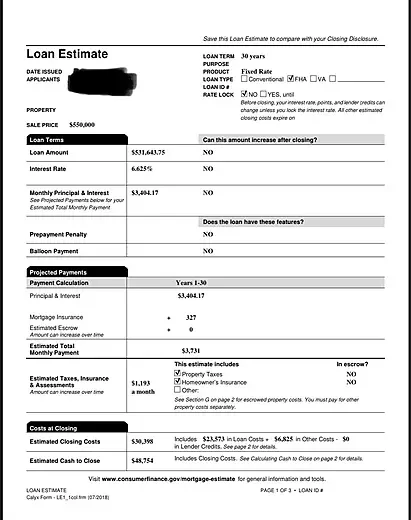
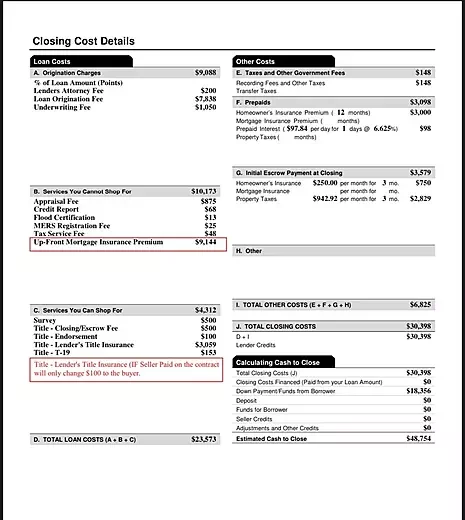
There are ways to save on closing costs, but before trying to save, you need a clear understanding of them. On the Loan Estimate, closing costs are divided into TWO sections. For more detailed information, see the CFPB’s guide to the Loan Estimate.
Loan Costs and Other Costs
Loan Costs = Section D = Section A + Section B + Section C
Section A: These are your lender charges, which include origination charges and the underwriting fee. These charges are tied to the offered interest rate and loan terms (such as having or not having a prepayment penalty or a balloon payment). You can shop this section among different lenders or mortgage brokers.
Section B: This section covers the credit report, appraisal report, and flood certificate and, for government loans, the upfront mortgage insurance. You cannot shop for these, and the fees are fairly fixed. If your loan is not a government loan, you do not need to worry about upfront mortgage insurance.
Section C: This section includes fees such as the escrow fee, title fee, hazard insurance, and any related fees. You can shop for this section.
Other Costs = Section I = Section E + Section F + Section G + Section H
Section E: This section includes all taxes and government fees and is not negotiable.
Section F: This section covers all prepaid items, such as prepaid interest and taxes.
Section G: If you decide to include taxes and insurance in your monthly payment, the lender needs to create a reserve account for you. This account is your own money, and if you sell, refinance, or decide to cancel, the money comes back to you.
Section H: This section is the owner’s title policy. It is entirely optional, not mandatory, but by law its estimated fee must be disclosed if you decide to have it.
Total Closing Costs = Loan Costs + Other Costs = Section D + Section I = Section J
Section J: Under this section you can see Lender Credits, which you can negotiate with your loan officer to offset part or all of your closing costs. A lender credit may come with a higher interest rate.
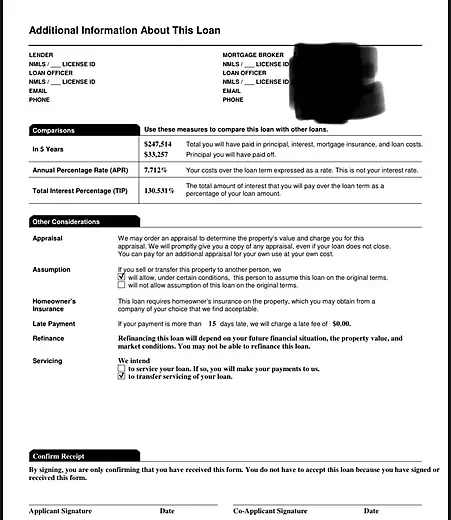
When your file is submitted to a lender, the lender must send you the “Initial Loan Estimate.” It normally gets emailed to you, along with other disclosures, within the first 3 days, and you need to e-sign it before the file goes to underwriting. Just remember: signing the initial disclosures does NOT create any obligation for you, and throughout the process your loan program might even change.
Loan Estimate